
Most food truck owners have three or four financial "systems" running at once, and none of them talk to each other. There's the spreadsheet where you track daily sales. The bank balance you glance at before ordering meat. The gut feeling that tells you whether a $600 event deposit is worth blocking a Saturday for. And the recipe costs you calculated once, eighteen months ago, and never updated.
Each one works fine in isolation. The problem is that real decisions cut across all of them. When someone emails asking if you can cater their kid's graduation for a $400 flat fee, that single yes-or-no touches your per-stop margins, your reserve for the slow month coming up, your deposit terms, and whether you'll have cash to cover payroll two Fridays from now. If those numbers live in separate places, you end up guessing — and guessing is how trucks with strong sales still run out of money.
The four pieces that have to connect
A truck's finances break down into four moving parts. Most operators track maybe two of them well.
-
Per-stop contribution margin — what each stop actually leaves in your pocket after the costs that stop caused.
-
Rolling weekly cashflow — money in and out, week by week, forward-looking not backward-looking.
-
Reserve sizing — how much cash you should be holding to survive the normal bad weeks.
-
Event and contract commitments — deposits owed to you, deposits you owe, and the decision logic for whether a bid is worth it.
These have to live in one model because each one feeds the next. Contribution margin tells you which stops are worth running. The sum of those margins across a week feeds cashflow. Cashflow volatility tells you how big your reserve needs to be. And your reserve and cash position determine which event bids you can actually afford to say yes to — even profitable ones can sink you if the deposit terms are wrong and cash is tight.
When these are disconnected, here's what typically happens: a truck books a big catering gig at a great margin, feels flush, spends the deposit on a new wrap and inventory, then hits a three-week stretch of rained-out lunch stops and can't make rent on the commissary. The event was profitable. The timing killed them. A connected model catches that before you sign.
Start with contribution margin, not "profit"
The single most useful number in this whole model is per-stop contribution margin, and it's not the same thing as profit. Contribution margin is revenue minus the costs that vary with that stop — food, the labor for that shift, fuel to get there, event fees, generator propane, disposables. It deliberately ignores your fixed monthly costs like insurance, truck payment, and commissary rent.
Stop losing sales to poor planning.
Grubzly helps you plan routes, track inventory, and maximize daily sales effortlessly.
- Real-time route optimization
- Inventory tracking & alerts
- Mobile sales & reporting
No credit card required
Why ignore fixed costs at the stop level? Because your insurance doesn't get cheaper if you skip a Tuesday. When you're deciding whether a specific stop is worth running, the only costs that matter are the ones that stop creates.
Here's a worked example for a single lunch stop:
| Line | Amount |
|---|---|
| Gross sales | $920 |
| Food cost (31%) | –$285 |
| Shift labor (2 people, 5 hrs loaded) | –$180 |
| Fuel + drive time | –$40 |
| Disposables / propane | –$35 |
| Card processing (~2.7%) | –$25 |
| Contribution margin | $355 |
| CM % | ~39% |
That $355 is what the stop contributes toward covering your fixed costs and profit. If your fixed costs run around $6,800 a month — roughly $1,570 a week — you now know something concrete: you need about four-and-a-half stops like this one every week just to break even before you make a dime.
That framing changes decisions. A stop pulling $180 in gross with a $120 contribution margin isn't "bad revenue" — it might still be worth running if it's on the way to a better stop and covers its own costs. But a stop that contributes $60 after you've paid two people and driven 40 minutes is quietly losing you money even though the POS shows a positive sale. If you've already built a per-stop P&L habit from recipe costing and portion SOPs, you're most of the way there — this just layers in the location-specific costs on top of plate costs.
Roll it forward: the weekly cashflow layer
Contribution margins tell you which stops earn. Cashflow tells you whether you'll have money in the account when bills hit. These are different questions and trucks confuse them constantly.
A rolling weekly cashflow isn't a record of what happened — it's a 6-to-8 week forward projection you update every week. Each week has a starting cash balance, expected inflows, scheduled outflows, and an ending balance that becomes next week's start. The value is in seeing the dips before they arrive.
Here's a simplified four-week rolling view for a single truck:
| Item | Week 1 | Week 2 | Week 3 | Week 4 |
|---|---|---|---|---|
| Starting cash | $4,200 | $5,010 | $3,140 | $2,020 |
| Stop CM (net) | +$1,850 | +$1,420 | +$1,680 | +$2,300 |
| Event deposit in | — | — | +$400 | — |
| Fixed costs | –$1,570 | –$1,570 | –$1,570 | –$1,570 |
| Owner draw | –$800 | –$800 | –$800 | –$800 |
| Quarterly insurance | — | –$920 | — | — |
| Sales tax remittance | –$670 | — | –$830 | — |
| Ending cash | $5,010 | $3,140 | $2,020 | $1,150 |
Model quarterly and annual lump-sum outflows like insurance and taxes as separate line items so they don't surprise your weekly projection.
Look at Week 4. On paper the truck is doing fine — contribution margins are healthy, sales are up. But cash is drifting toward a level where one bad week or one surprise repair puts you underwater. That's exactly what a rolling model catches while there's still time to react: pick up a Saturday event, delay the owner draw, push a supplier payment.
Two outflows people consistently forget to model: quarterly or annual lump sums (insurance, permits, maintenance) and tax remittances. Sales tax especially feels like your money until it isn't — if you're operating across jurisdictions, keeping that liability visible in the cashflow model instead of buried in the bank balance is the whole point of a clean multi-city tax remittance system. The deeper mechanics of building this projection are covered in the weekly cashflow model — here we're focused on how it plugs into the rest.
Sizing your reserve with a rule, not a vibe
Ask most operators how much cash they keep in reserve and the answer is "whatever's left" or "I try to keep a couple grand." Neither is a rule. A reserve should be sized off your actual volatility, not a round number that feels comfortable.
The approach that works: base your reserve on your worst realistic run of weeks, not your average. Pull your last six months of weekly ending-cash figures. Find your typical bad week — not the disaster, just the bottom-quartile normal-bad week. Then decide how many consecutive bad weeks you need to survive without panic-selling equipment or missing payroll.
A workable formula for a single truck: Reserve target = (weekly fixed costs + owner draw) × cushion weeks + one worst-case repair
-
$2,370 × 4 = $9,480
-
Plus $3,500 repair buffer
-
Reserve target ≈ $13,000
That number will feel high the first time you see it. Most single-truck operators run on far less, which is exactly why a rained-out fortnight or a blown compressor turns into a borrowing emergency. You don't have to hit the target overnight — but now you have an actual target, and every week your cashflow model tells you whether you're building toward it or drifting away.
The reserve math also changes as you scale. A second truck doesn't double your reserve need — it can actually smooth volatility if your stops are spread across different parts of the city. But it adds a second set of fixed costs and a second failure point. The rule holds; the inputs change.
The event-bid decision tree
This is where the model earns its keep, because event bids are the decisions where operators most often override good numbers with excitement. A $1,200 booking sounds fantastic until you work out it blocks two proven $355-margin lunch stops, requires $300 in extra prep labor, and pays net-30.
-
Does it cover its own contribution margin? Estimate event revenue minus all variable costs — food, extra labor, travel, generator, packing. If the CM is below what you'd earn running your normal stops that day, stop here unless there's a clear strategic reason to take the hit.
-
What's the opportunity cost? Subtract the contribution margin of the stops you're giving up. The event has to beat your displaced earnings, not zero.
-
What are the deposit and payment terms? A profitable event that pays net-45 with no deposit is a cashflow problem wearing a profit costume. Require a deposit large enough to cover your out-of-pocket variable costs before the event date.
-
Does taking it push any cashflow week below your reserve floor? Drop the event into the rolling model. If Week 3 dips under your reserve target because you fronted $500 in inventory, the answer might be "yes, but only with a bigger deposit."
-
Does it carry contract risk? Insurance requirements, exclusivity clauses, cancellation terms. This is where a proper contract and deposit structure for private events keeps a good bid from turning into a liability.
Here's that process applied to a real-feeling bid:
-
Event revenue
$1,150 flat, 3 hours
-
Variable costs
food $310, extra prep labor $180, travel/generator $70, packing $30 → CM = $560
-
Displaced stops that day
one lunch stop at $355 CM
-
Net gain over doing your normal day
~$205
-
Terms
client offered net-30, no deposit
The margin's fine. The terms are the problem. Net-30 with no deposit means you front $310 in food and wait a month for $1,150 while your cashflow model already shows a Week 4 dip. The correct answer isn't "no" — it's "yes, with a 50% deposit on booking." Working through the numbers turned a risky yes into a safe one. That's the entire point of connecting the pieces.
When this level of modeling makes sense — and when it doesn't
When it's worth it: You're running more than a couple of stops a week, you take on events or catering, and you've had at least one month where sales looked fine but cash got scary tight. The moment your decisions involve real tradeoffs — this event vs. that stop, this deposit vs. that payroll — you need the connected view.
When it's overkill: If you run one truck, one weekly market, cash-only, with no events and no employees, a full rolling model is more machinery than you need. A simple contribution-margin check and a bank buffer will do. Don't build a system to manage complexity you don't have yet.
Who should not try to run this in their head: Anyone with more than one truck, anyone with net-terms catering clients, anyone whose owner draw is variable. Once there are multiple cash timing streams, mental math fails silently — you feel fine right up until the week you don't.
A short real scenario
A two-truck taco operation was doing somewhere between $18k and $21k a month in sales and still couldn't figure out why the account kept scraping bottom around the 25th. Their per-stop numbers were solid, mid-30s contribution margins. The trouble surfaced when the pieces finally landed in one place.
Three things came up. First, two recurring weekday stops were contributing under $90 each after loaded labor — busy stops that felt productive but barely paid for themselves. Second, they were routinely spending catering deposits the week they landed, then getting squeezed when fixed costs and a net-30 event collided in the same week. Third, they had no reserve rule at all. The "reserve" was whatever the balance happened to be.
Nothing exotic changed. They dropped one weak stop and renegotiated the other, moved to a standard 40% deposit on catering, and set a reserve target around $11k that they built toward over roughly three months. Sales didn't jump. But the end-of-month cash panic stopped, and they started saying yes to the right events instead of every event. The difference wasn't more revenue — it was the same revenue, finally coordinated.
Where the model actually lives
You can build all of this in a spreadsheet, and you should start there — copy the per-stop P&L structure, the rolling cashflow grid, and the reserve formula into tabs you touch every Monday. The templates matter less than the routine of updating them.
The friction shows up as you grow. Two trucks and a handful of standing events means your contribution margins, cash timing, and deposit tracking start changing faster than you want to re-key by hand. This is where AI-powered operational software earns its place — not by replacing your judgment, but by keeping per-stop numbers, the rolling cashflow, and deposit rows updated from the same data instead of three disconnected sheets that drift out of sync by Wednesday. When your POS totals and event deposits flow into one place, the decision logic runs on current numbers instead of last month's.
Here's a simple visual of how the pieces fit together.
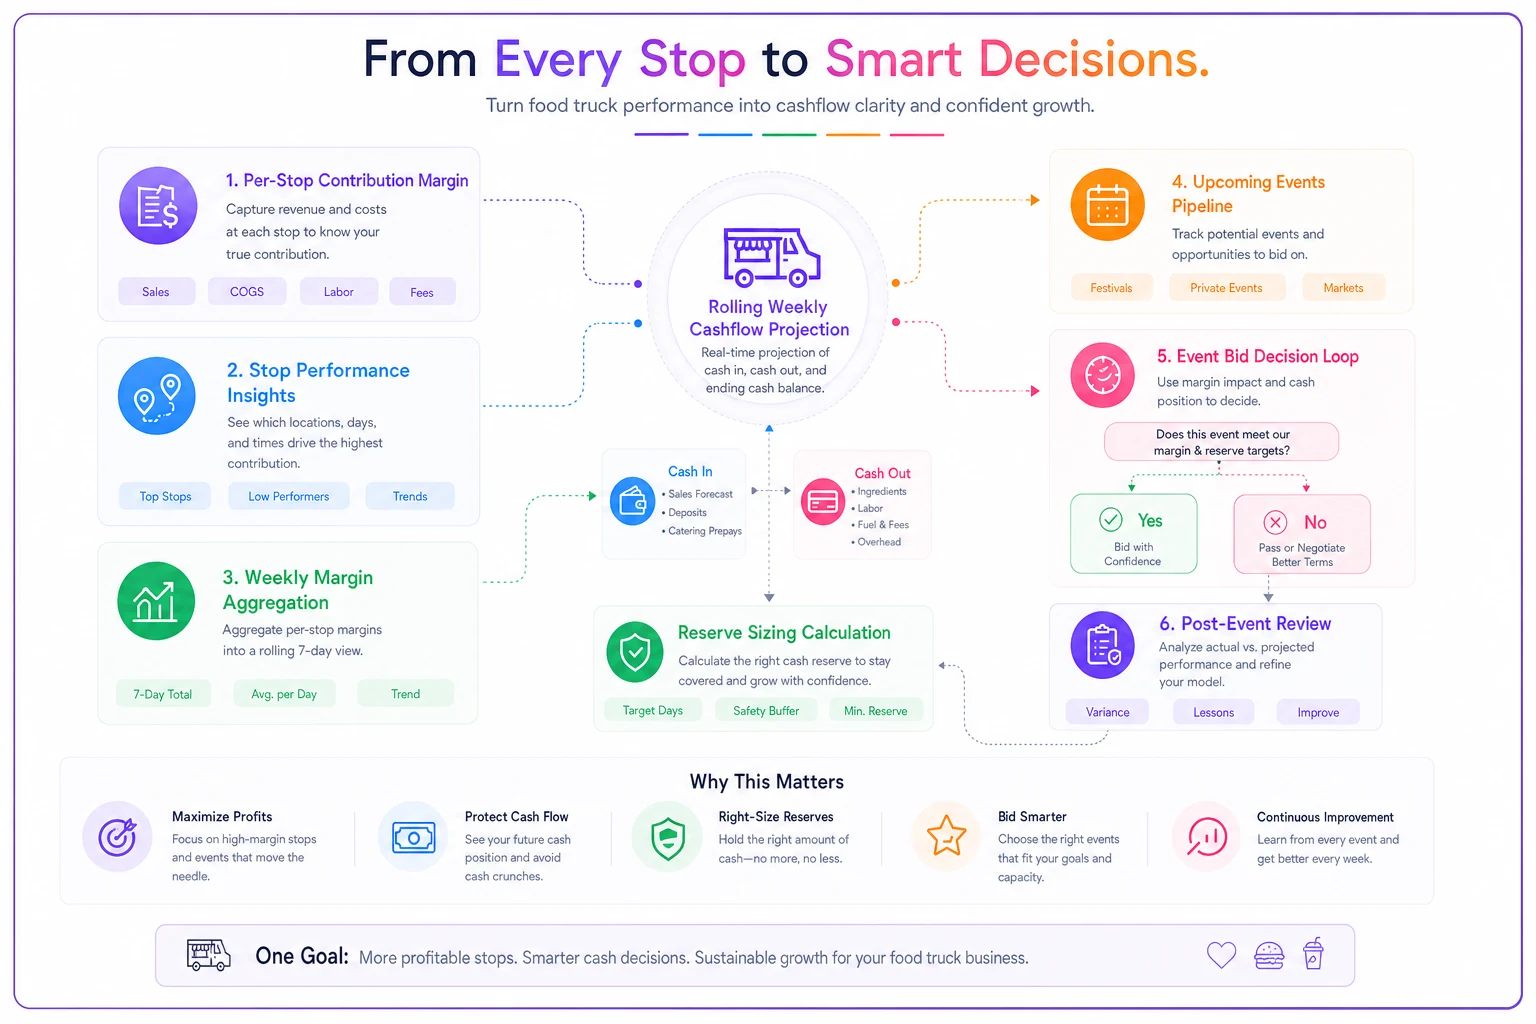
Automating the data plumbing frees you to actually make the calls the model is built to inform.
The core idea is simple even if the setup takes a weekend: your stops, your cash, your reserve, and your bids are one system. Decisions that ignore any one of them will eventually cost you. Build the model once so that every "should I take this?" has a real answer waiting — not a guess.
Ready to drive your food truck business forward?
Join 2,000+ food truck operators relying on Grubzly to boost efficiency, increase sales, and delight customers.